How to Verify ABA Therapy Insurance Benefits Before Starting Services
If you’re considering Applied Behavior Analysis (ABA) therapy for your child, one of your first questions may be: Does my insurance cover ABA therapy?
Understanding insurance benefits can feel complicated, especially when you’re already navigating evaluations, diagnoses, and treatment options for your family.
The good news is that you don’t have to figure everything out on your own.
ABA therapy insurance verification helps families understand their coverage, potential out-of-pocket costs, provider network requirements, and whether authorization is needed before treatment begins.
In this guide, we’ll explain how to verify ABA therapy insurance benefits, what questions to ask your insurance company, and how to prepare for the next steps.
What Is ABA Therapy Insurance Verification?
ABA therapy insurance verification is the process of reviewing a health insurance plan to determine whether it includes benefits for Applied Behavior Analysis services.
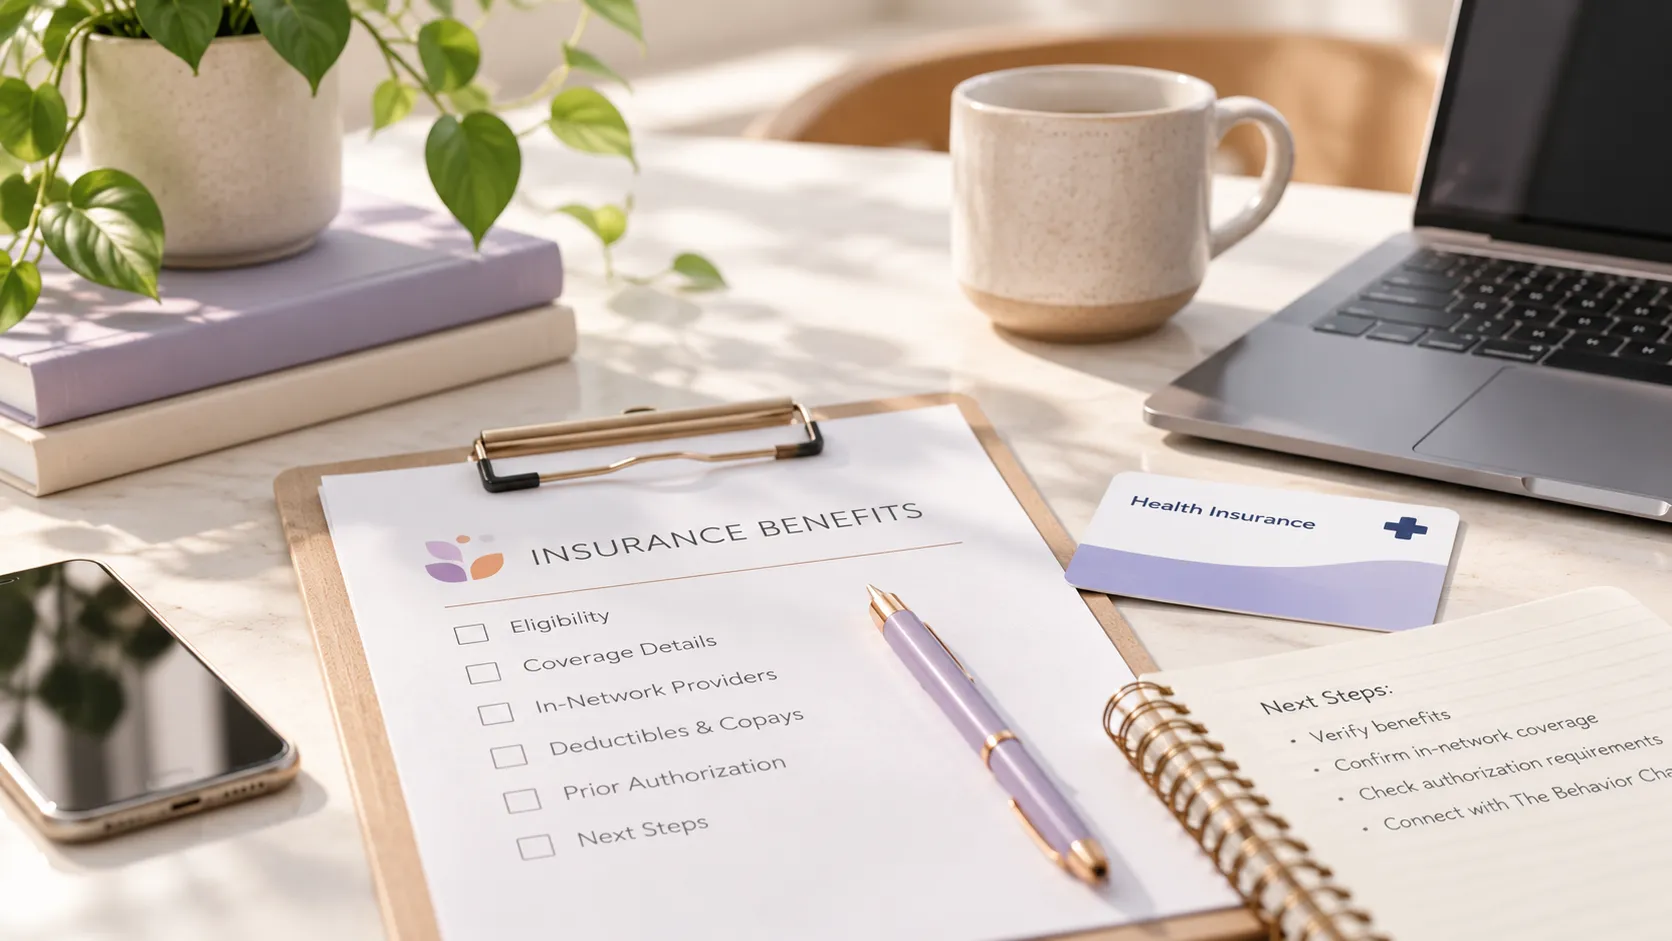
This process helps identify important coverage details, including:
- Whether the insurance policy is currently active.
- Whether ABA therapy is a covered benefit.
- Whether a specific ABA provider is in-network.
- Whether deductibles, copays, or coinsurance apply.
- Whether a referral, diagnosis, or prior authorization is required.
- Whether the plan has additional limitations or documentation requirements.
Insurance verification is an important first step, but it is not a guarantee that an insurance company will approve or pay for every service.
Final coverage and payment decisions depend on the specific policy, medical necessity requirements, authorization status, and other plan provisions.
Step 1: Confirm Your Insurance Eligibility
Before exploring ABA therapy benefits, confirm that your child’s health insurance coverage is active.
Insurance eligibility refers to whether the individual is currently enrolled in a health plan and eligible to receive benefits under that policy.
To begin, gather the following information:
- Insurance company name.
- Member identification number.
- Group number, if applicable.
- Policyholder’s name and date of birth.
- Child’s name and date of birth.
- Insurance card and relevant plan documents.
You can usually confirm eligibility through your insurer’s member portal, by contacting the customer service number on your insurance card, or with assistance from a prospective ABA therapy provider.
Helpful tip: If your family recently changed insurance plans, verify the effective date and whether the new policy includes ABA therapy benefits.
Step 2: Check Whether Your Insurance Covers ABA Therapy
Once your insurance eligibility is confirmed, the next step is to determine whether your plan includes ABA therapy coverage.
Coverage requirements vary by insurance company, plan type, state, and individual policy.
Some plans cover ABA therapy when specific medical necessity criteria are met. Others may require additional documentation or impose particular provider qualifications.
When reviewing your benefits, ask:
- Does my plan cover Applied Behavior Analysis therapy?
- Is an Autism Spectrum Disorder (ASD) diagnosis required?
- What clinical documentation is needed?
- Are ABA assessments and treatment sessions covered?
- Are there specific provider or treatment requirements?
- Are there any applicable exclusions or limitations?
Understanding these details early can help prevent unexpected complications during the intake process.
Does Insurance Cover ABA Therapy in Texas and Florida?
Many health insurance plans in Texas and Florida provide some level of autism-related coverage, which may include ABA therapy.
However, coverage is not identical across all policies.
State insurance requirements, employer-sponsored plan structures, Medicaid program rules, and individual plan provisions can affect which services are covered.
For example, some self-funded employer plans are governed by federal rules rather than all state insurance mandates.
Families should verify their specific benefits rather than assuming that coverage is automatic.
Step 3: Find Out Whether Your ABA Provider Is In-Network
An important part of verifying ABA therapy insurance benefits is determining whether your preferred provider participates in your insurance network.
What Does In-Network Mean?
An in-network ABA provider has a contractual relationship with your insurance plan or its applicable network.
Receiving services from an in-network provider may reduce your out-of-pocket expenses compared with using an out-of-network provider.
However, the actual cost depends on your specific benefits.
What If an ABA Provider Is Out-of-Network?
Out-of-network coverage varies considerably.
Depending on your plan, you may have higher deductibles, higher coinsurance, limited reimbursement, or no out-of-network benefits for certain services.
Before choosing a provider, ask:
- Is this ABA therapy provider in-network with my specific plan?
- Is the provider’s location included in my network?
- Are the individual clinicians covered under the applicable network arrangement?
- Does my plan offer out-of-network ABA benefits?
- Will I need an authorization or referral?
Important: An ABA organization may accept an insurance company without participating in every plan offered by that company.
Always verify your specific policy.
Step 4: Understand Deductibles, Copays, and Coinsurance
Even when ABA therapy is covered by insurance, families may be responsible for certain out-of-pocket expenses.
Understanding the most common insurance terms can help you plan ahead.
Deductible
A deductible is the amount you may need to pay for covered healthcare services before your insurance plan begins paying according to its benefit structure.
For example, if your plan has a $1,500 deductible, you may be responsible for eligible healthcare costs until the applicable deductible has been met.
Some services may be covered before the deductible is met, depending on the policy.
Copay
A copay is a fixed amount you pay for a covered healthcare service when your plan requires one.
For example, a plan might require a $25 copay for a particular type of visit.
ABA therapy cost-sharing may work differently from standard office visits, so confirm the applicable benefit category.
Coinsurance
Coinsurance is the percentage of covered costs you may be responsible for after applicable deductible requirements are satisfied.
For example, if a covered service has an allowed amount of $200 and your coinsurance is 20%, your share would generally be $40, assuming the deductible has been met and no other plan provisions change the calculation.
Out-of-Pocket Maximum
Your out-of-pocket maximum is the most you generally pay for covered, in-network services during a plan year before your plan pays 100% of covered in-network benefits.
Not every expense counts toward this limit. Premiums, noncovered services, and certain out-of-network charges may be excluded.
Helpful tip: Ask your insurer how ABA assessments, direct therapy sessions, and caregiver training are classified for cost-sharing purposes.
Step 5: Determine Whether Prior Authorization Is Required
Many insurance plans require prior authorization before certain ABA therapy services can begin.
Prior authorization is a review process in which the insurance company evaluates whether a proposed service meets its coverage and medical necessity criteria.
Depending on the plan, authorization requests may require:
- A documented autism diagnosis.
- A referral or prescription from a qualified healthcare professional.
- Relevant diagnostic or clinical records.
- An initial ABA assessment.
- A proposed treatment plan.
- Supporting medical necessity documentation.
The specific requirements vary.
Does Prior Authorization Guarantee Payment?
No. Prior authorization is not an unconditional guarantee of payment.
Claims may still be subject to eligibility, benefit limitations, service documentation, and other applicable plan requirements.
For this reason, families should confirm both the authorization requirements and the broader insurance benefits before starting treatment.
Step 6: Ask for a Summary of Your ABA Therapy Benefits
After completing the insurance verification process, request a clear explanation of the information available.
Ideally, your benefits summary should address:
- Current insurance eligibility.
- ABA therapy benefit availability.
- In-network or out-of-network status.
- Deductible and cost-sharing requirements.
- Prior authorization requirements.
- Known limitations or documentation needs.
- Next steps before beginning services.
You may also want to keep a record of the date you contacted your insurance company, the representative’s name, and any reference number provided.
This documentation can be useful if you need to follow up later.
Step 7: Connect With an ABA Therapy Provider
Once you have a better understanding of your insurance benefits, you can begin exploring appropriate ABA therapy services for your child.
An ABA provider may help you understand the intake process, discuss your child’s needs, and identify any additional documentation required.
At The Behavior Change, we understand that navigating insurance can be one of the more confusing parts of seeking ABA therapy.
Our team can assist families in Texas and Florida with the initial benefits verification process and help explain the next steps toward accessing services.
Ready to Verify Your ABA Therapy Insurance?
You don’t have to navigate insurance terminology and benefit requirements alone.
Submit a benefits verification request to The Behavior Change, and our team can help you review available coverage information and understand the next steps.
Insurance verification does not guarantee coverage, authorization, or payment. All services remain subject to plan requirements, eligibility, and availability.
Frequently Asked Questions About ABA Therapy Insurance
How Do I Verify My Insurance Benefits for ABA Therapy?
You can contact your insurance company, review your member benefits portal, or request assistance from an ABA therapy provider. Verification should include coverage eligibility, ABA-specific benefits, network status, cost-sharing, and prior authorization requirements.
Can I Check ABA Therapy Coverage Without Calling My Insurance Company?
Yes. You may be able to review benefits through your insurer’s online member portal or request assistance from an ABA provider.
Additional confirmation from the insurance company may still be necessary.
How Do I Know If My Insurance Covers ABA Therapy?
Review your policy’s behavioral health and autism-related benefits, or contact your insurer to confirm whether ABA therapy is covered under your specific plan.
Ask about diagnostic requirements, provider networks, and prior authorization.
Do I Need Prior Authorization for ABA Therapy?
Many insurance plans require prior authorization for ABA assessments or ongoing treatment, but requirements vary. Your insurer or ABA provider can help clarify the authorization process for your plan.
Will I Have to Pay Out of Pocket for ABA Therapy?
Possibly. Your costs may depend on deductibles, copays, coinsurance, provider network status, and other plan provisions.
A benefits verification can help identify expected cost-sharing, although actual charges may differ.
Can I Start ABA Therapy Before Insurance Verification Is Complete?
It is generally advisable to confirm coverage and any required authorizations before starting services you expect insurance to pay for.
Beginning treatment without completing necessary insurance steps may create unexpected financial responsibility.
Take the Next Step Toward ABA Therapy
Understanding your insurance benefits is an important part of preparing for your child’s care.
By confirming eligibility, reviewing ABA coverage, checking provider network status, and understanding authorization requirements, you can make more informed decisions about starting therapy.
The Behavior Change is here to help families navigate the initial steps.